Profitable on paper, struggling for cash: why getting paid matters
September 21, 2026A business can be profitable, have plenty of work coming through the door and still find itself struggling to pay its bills.
It sounds contradictory, but it is one of the most important lessons in business:
Profit and cash are not the same thing.
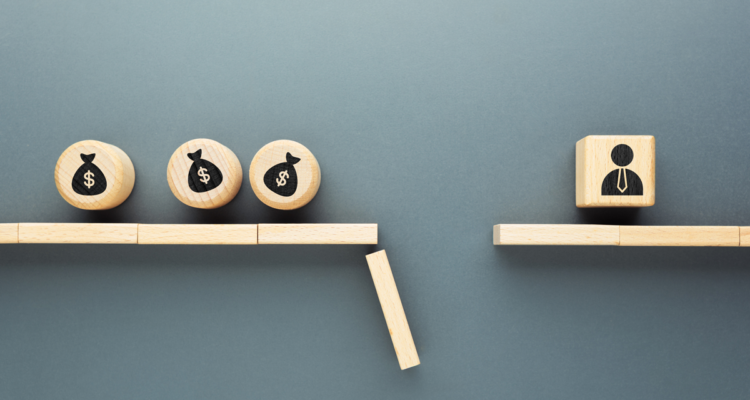
You might complete a $30,000 job and record $30,000 of revenue. But until your customer actually pays the invoice, that money isn’t sitting in your bank account.
Meanwhile, your employees still need to be paid. Your suppliers want their money. Rent, insurance and loan repayments continue. Then there are BAS payments, PAYG withholding, superannuation and other obligations.
That gap between earning money and receiving it can become a serious problem.
When your customer’s cash flow becomes your cash flow problem
Late payment isn’t simply an irritating administrative issue.
Imagine a customer who normally pays you within 30 days suddenly takes 60 or 90.
You may still have to pay suppliers who helped you deliver their work within 14 or 30 days. You may have already paid the wages associated with the job. GST and other obligations don’t necessarily wait until the customer decides to pay you.
Effectively, your business is financing your customer’s business.
One late payment may be manageable. But when several customers begin stretching their payment terms, the effect can accumulate surprisingly quickly.
The Australian Government’s Payment Times Reporting Regulator has identified continuing concerns around the time some large businesses take to pay their small-business suppliers. Recent data showed that the time taken by large businesses to pay 95% of their small-business invoices had increased from 58 days to 64 days.
For a small or medium business operating with limited cash reserves, those extra days matter.
The domino effect
There is another problem.
When Business A doesn’t get paid, it may start taking longer to pay Business B.
Business B then has less cash available to pay Business C.
Before long, somebody else’s debtor problem has travelled through the supply chain and become your problem.
The danger is responding to this by simply doing the same thing to your own suppliers.
Stretching creditors can provide temporary breathing room, but it doesn’t solve the underlying cash-flow problem. In some cases, it simply transfers financial pressure from one business to another while potentially damaging valuable supplier relationships.
Don’t wait until the bank account tells you there is a problem
One of the biggest mistakes a business owner can make is using today’s bank balance as their primary measure of financial health.
Your bank account tells you how much cash you have today.
It doesn’t necessarily tell you what will happen next month.
Good financial management means looking forward.
- How much is owed to you?
- How old are those debts?
- Which customers are consistently paying late?
- What bills are falling due?
- When are your BAS, tax and superannuation obligations coming up?
- What happens to your cash position if a major customer pays 30 days later than expected?
These are questions that management accounts, cash-flow forecasts and regular financial reporting can help answer.
Your debtors deserve attention
For many businesses, considerable effort goes into winning a new customer, quoting the work and completing the job.
Then the invoice goes out and everyone moves on to the next job.
That final part of the sales process deserves just as much attention.
There are some basic disciplines every business should consider:
- invoice promptly and accurately
- make your payment terms clear from the beginning
- regularly review aged debtors rather than waiting until debts become seriously overdue
- follow up overdue invoices consistently
- consider deposits or progress payments for larger projects
- understand the creditworthiness of customers before extending significant credit
- avoid becoming excessively dependent on one customer
- make sure somebody in the business is clearly responsible for debtor management.
None of these measures can guarantee that every customer will pay on time. They can, however, reduce the chances of an overdue account quietly developing into a much larger problem.
Look beyond the profit and loss statement
This is where having a good accountant involved in your business should mean considerably more than preparing an annual tax return.
At Indigo Financial, when we talk to business clients about performance, we’re interested in more than whether the business made a profit last year.
We want business owners to understand what is happening inside their business.
That includes profitability, cash flow, debtors, creditors, tax obligations, margins and the financial trends that may indicate a problem is developing.
A business experiencing tightening cash flow doesn’t necessarily have a bad business.
It may have a good business with poor debtor management. It may be growing faster than its working capital can support. Its payment terms may no longer suit the way it operates. Or its cash-flow forecasting may simply not have kept pace with the business.
The important thing is identifying the cause early enough to do something about it.
Cash flow problems rarely improve by ignoring them
If your sales are strong but cash always seems tight, your debtors are getting older or you’re increasingly relying on an overdraft or credit card to meet everyday expenses, those are signals worth investigating.
Don’t wait until an overdue customer account means you can’t meet your own obligations.
The best time to address a cash-flow problem is while you still have options, not when you have run out of them.
Talk to Indigo Financial early…
- Look at the numbers.
- Understand where the pressure is coming from and put appropriate systems in place.
Because making the sale is important, but getting paid for it is what keeps you in business.
Contact Indigo Financial on (08) 8212 8585 if you need help with understanding any of your accounting, taxation and business development needs.
Note: The material and contents provided in this publication are informative in nature only and do not take into account your individual circumstances. It is not intended to be advice and you should not act specifically on the basis of this information alone. If expert assistance is required, professional advice should be obtained.
Sources
Australian Government, Payment Times Reporting Scheme, Helping small business
Australian Government, Payment Times Reporting Regulator, Regulator’s update – January 2026
Australian Taxation Office, Manage your business cash flow
Australian Taxation Office, Cash Flow Kit